
LoadingLoading

 1 / 4
Quantitative analytics platform
Pre-order live · £490 · Waitlist closed
Developed in C++ for uncompromising speed and reliability, with an extensive library of over 8,000 functions, TQH TERMINAL is used interactively for ad-hoc analytics or to implement solutions for the Quant trading or sales desk.
Waitlist complete — book closed. Pre-order TQH TERMINAL now at £490.00. Pay securely with stablecoins via Paymento for launch-day delivery.
Overview
TQH TERMINAL provides a complete environment for quantitative analysis, data manipulation, and risk analytics. Developed in C++ from the ground up, it delivers uncompromising performance for the most demanding financial workflows.
With over 8,000 built-in functions covering fixed income, derivatives, equities, FX, and commodities, TQH TERMINAL enables quants, traders, and risk managers to build, test, and deploy sophisticated analytics in record time. Whether you're pricing a single exotic option or running a full portfolio risk sweep across thousands of positions, the platform scales from quick interactive queries to production-grade automated workflows without switching tools.
TQH TERMINAL was built by practitioners who understood a simple problem: most quant tools force a tradeoff between speed of experimentation and robustness of deployment. You prototype in one language, then rewrite everything in another to get it production-ready. TQH TERMINAL closes that gap. Developed natively in C++ with a console-first interactive environment, the same workflow you use to test an idea is the same code path that runs in production on the trading desk no rewrite, no translation layer, no drift between research and execution.
Executive Announcement
We are excited to announce full historical market data coverage in TQH Terminal for the two benchmark instruments most requested by our quantitative trading community: NQ E-mini Nasdaq-100 Futures and ES E-mini S&P 500 Futures, both on CME Globex.
Together, these two contracts represent over 65% of global equity index futures trading volume. Coverage now spans all three fundamental data depth tiers ranging from multi-year top-of-book tick archives to order-level Market By Order (MBO) granularity.
Data Depth Tiers
Why It Matters
Most retail backtesting engines rely on aggregated time bars (1-minute, 5-minute, or 1-hour OHLCV). While sufficient for slow momentum strategies, bar-based backtests silently make catastrophic assumptions that destroy live performance.
01
Assuming any order placed at a limit price is immediately filled without slippage.
02
Ignoring that limit orders sit at the back of a multi-thousand contract queue on CME Globex.
03
Missing order cancellations and phantom liquidity spikes that occur in sub-millisecond windows.
Strategies validated purely on aggregated bars routinely experience 40% to 70% alpha decay in live production. Order-level MBO and L2 depth allow you to model the exact mechanics that determine your true P&L: queue priority, true available liquidity, and real-world execution slippage.
Microstructure
NQ operates primarily on strict Price-Time Priority. Your place in the queue dictates your fill sequence down to the millisecond. With TQH Terminal's Level 3 MBO data backtesters can accurately simulate order placement by appending orders to the true historical queue at the moment of entry.
ES employs a split FIFO / Pro-Rata algorithm at outer price levels. Level 3 MBO data enables exact fill latency measurement, tracking order cancellations ahead of your position, and precise queue-jump simulation.
Technical Specifications
Specifications
Capabilities
Full historical market data coverage across Level 1 (L1 BBO tick archives from 2010 to present), Level 2 (L2 DOM 10-level depth), and Level 3 (L3 MBO order-level events A/M/C/E with 64-bit order IDs) for NQ and ES index futures.
Process and analyze financial data in real-time with a lightning-fast native C++ engine and over 8,000 built-in functions. Stream live market data directly into your analytics, recalculate risk metrics on every tick, and get the answers you need before the market moves on without you.
Support for equities, fixed income, derivatives, FX, and commodities across all major asset classes. A single unified data model and function library means you're not maintaining separate toolkits for each desk one terminal covers your entire book.
Available in desktop and enterprise editions to meet the diverse quantitative analysis needs within large financial organisations. Start with a single desktop license for individual research, then scale to an enterprise deployment with centralized data feeds, shared function libraries, and team-wide governance as your needs grow.
Used interactively for ad-hoc analytics or to implement solutions for the Quant trading or sales desk. TQH TERMINAL's console-first design means you can explore a dataset, test a hypothesis, and ship a working tool in the same session ideal for fast-moving desks where the cost of a slow iteration loop is measured in basis points.
With over 8,000 built-in functions as your starting point, TQH TERMINAL also supports custom function definitions, so quant teams can encode proprietary models, house pricing conventions, and bespoke risk measures directly into the platform alongside the standard library.
TQH TERMINAL's C++ execution engine is engineered for the workloads that matter most in financial markets: large matrix operations, Monte Carlo simulation, time-series analysis, and curve construction all optimized to run with minimal latency, even at scale.
Gallery
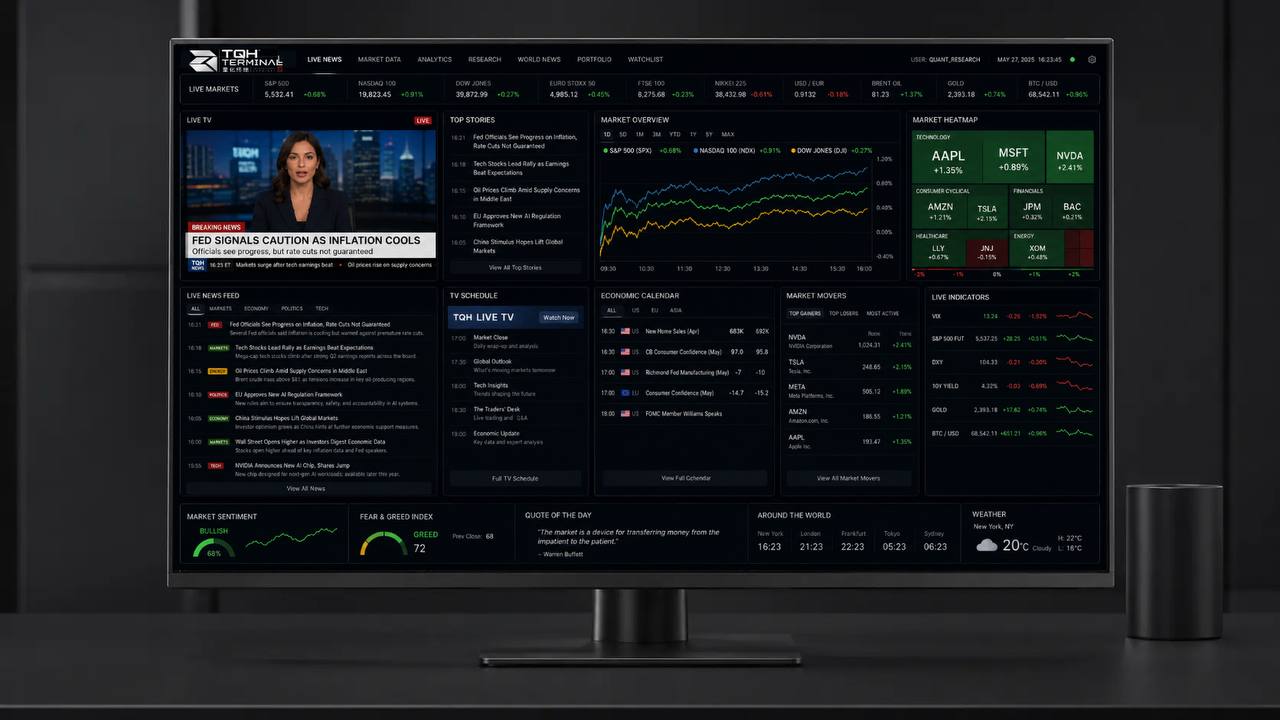
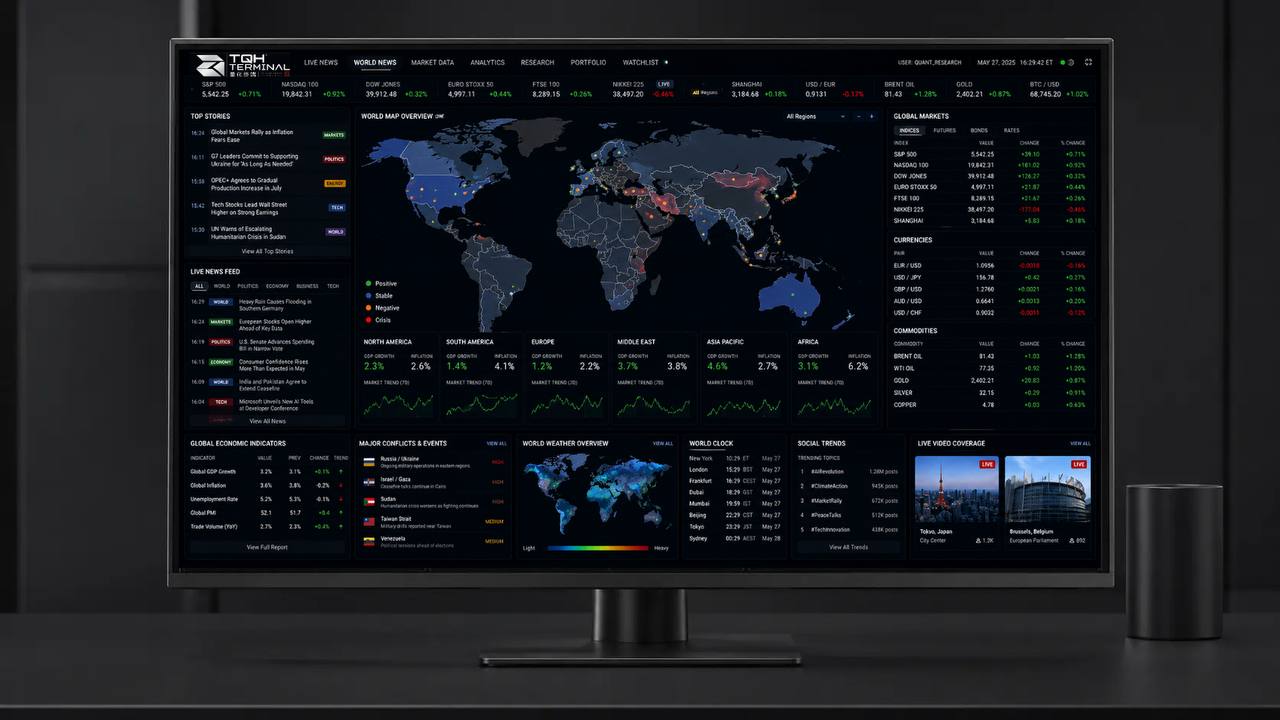
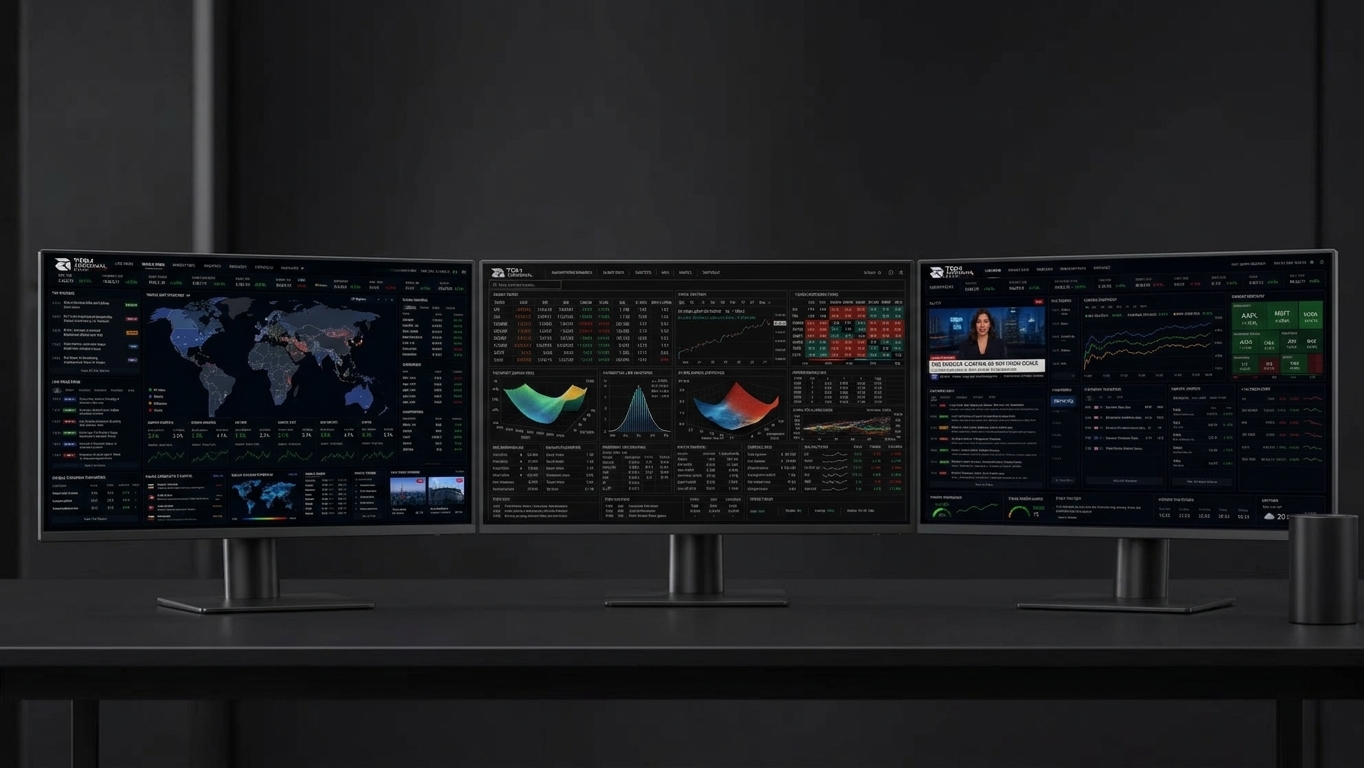
Audience
Building and backtesting pricing models, calibrating curves, and researching new strategies without leaving a single environment.
Who need fast, reliable analytics at the point of decision spreads, greeks, scenario P&L without waiting on a separate research team.
Running portfolio-wide stress tests, VaR calculations, and exposure analysis across asset classes.
Generating client-ready pricing and structuring outputs on demand during live conversations.
Keep exploring
Waitlist closed. Pre-order now at £490 · Secure checkout · Launch-day delivery.